4 Crucial Personal Finance Basics Every Beginner Needs to Know
Imagine waking up each morning feeling confident about your money choices. No more worrying about unpaid bills, surprise expenses, or unclear savings goals. For many, personal finance feels overwhelming, but it doesn’t have to be. By embracing foundational principles, you’ll find empowerment, peace of mind, and the stepping stones to a brighter future.
Whether you are just starting your financial journey or want to get back on track, understanding personal finance basics is essential. These building blocks equip you to handle money responsibly, make proactive decisions, and pursue your dreams with courage.
Why Personal Finance Matters for Everyone
Money touches every aspect of our lives. From daily coffee purchases to once-in-a-lifetime adventures, the way we manage finances has a ripple effect on our well-being, relationships, and opportunities.
For beginners, diving into personal finance can feel like navigating a foreign language. However, with a practical, step-by-step approach, anyone can learn to control spending, prepare for uncertainty, and grow wealth over time. It all starts with a willingness to learn and a determination to change.
Building Your First Budget: The Foundation of Success
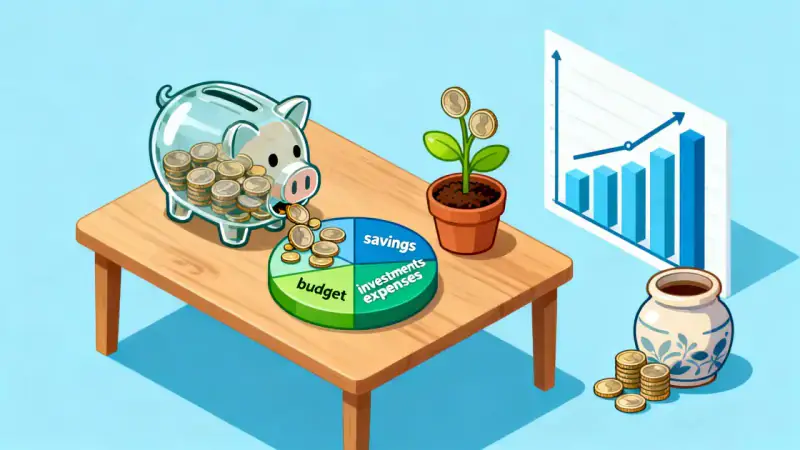
The first step in mastering your finances is creating a budget. Think of a budget as your financial roadmap. It helps you visualize where your money comes from and where it goes every month.
Without a budget, it’s easy to overspend or forget about irregular expenses like annual subscriptions or car repairs. A good budget puts you in control, eliminating guesswork and anxiety.
- Track all sources of income, including your salary, side hustles, or benefits.
- List your monthly expenses: rent, groceries, utilities, transport, leisure, and savings.
- Look for spending patterns and identify areas to cut back if needed.
- Assign each dollar a purpose, even if it goes toward fun or occasional treats.
A budget isn’t about restriction—it’s about prioritizing what matters to you most. When you tell your money where to go, you start steering your own financial narrative.
Creating an Emergency Fund: Your Personal Safety Net
Life is full of surprises—medical bills, job loss, urgent repairs. An emergency fund acts as a financial buffer, offering peace of mind during uncertain times.
Aiming for three to six months’ worth of expenses is a solid goal, but don’t be discouraged if you’re starting from scratch. Every little bit helps. Set up a separate savings account, contribute regularly— even $10 or $20 a week adds up over time.
- Decide on a reachable target for your first goal—perhaps $500 or $1,000 to begin.
- Automate a small, consistent contribution from your paycheck.
- Only use this money for genuine emergencies, not routine spending.
An emergency fund lets you meet challenges with resilience rather than resorting to high-interest debt or credit cards. It’s the difference between crisis and calm.
Managing Debt: Taking Back Control
Debt can feel overwhelming and unending, but proactive management transforms it into a conquerable challenge. Facing your debts openly is the first courageous step toward financial freedom.
List all debts: student loans, credit cards, car payments, and any personal loans. Note their balances, interest rates, and minimum monthly payments. This creates transparency and helps you develop a practical plan.
| Debt Type | Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Credit Card | $2,000 | 20% | $50 |
| Student Loan | $10,000 | 5% | $100 |
| Car Loan | $5,000 | 7% | $150 |
Choose a repayment method that motivates you. Some prefer the “avalanche” method—targeting high-interest debt first to save on interest. Others go with the “snowball” approach—paying off smallest balances for psychological wins and momentum.
Always pay at least the minimum on all debts to avoid penalties, and channel any extra funds toward your chosen focus. Each payment brings you one step closer to financial independence.
Saving and Investing: Securing Your Future
The fourth core principle for beginners is learning to save and invest. It’s more than just setting money aside—it’s about letting your money work for you.
Start with simple, attainable savings goals—a vacation, upgrading technology, or growing your emergency cushion. Once savings become a habit, open a retirement or investment account, such as a 401(k) or IRA, and begin with small contributions.
The magic of investing lies in compound growth—a little invested early can become much more over time. Don’t worry if you can’t contribute a lot. Consistency is key.
- Start with employer-sponsored retirement plans if offered.
- Research basic stocks, mutual funds, or index funds as beginner-friendly investments.
- Reinvest your earnings to let compounding work in your favor.
Gradually, you’ll see your savings and investments grow, giving you more choices and less stress about your future. Financial freedom becomes not just a dream, but a reality within your grasp.
Bringing It All Together: Your Journey Forward
Learning personal finance basics can feel daunting, but each step forward builds momentum. Begin with a simple budget, protect yourself with an emergency fund, tackle debt head-on, and let your savings grow.
There will be setbacks, but persistence pays off. Celebrate small victories: paying off a credit card, reaching your first $1,000 in savings, or sticking to your budget for a whole month.
Your financial journey is your own. Take pride in your progress and remember that it’s never too late to start. Every positive choice, however small, adds up over time.
Start today—your future self will thank you for it.